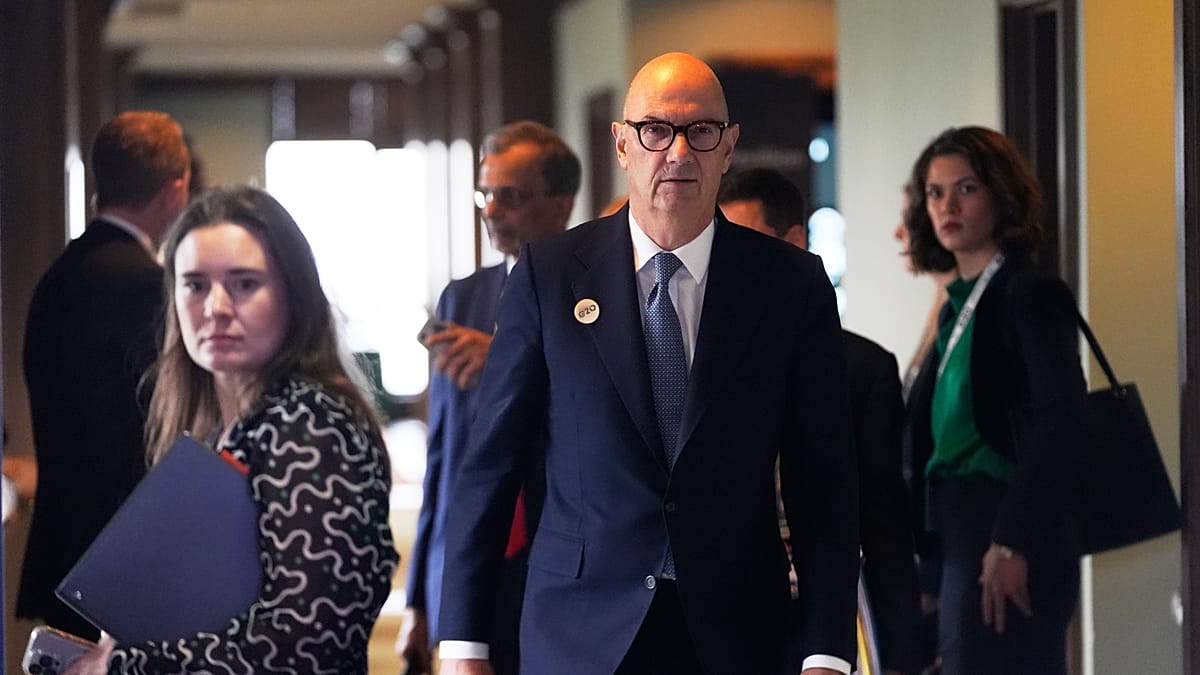
France’s Prime Minister Sébastien Lecornu is set to unveil the country’s 2027 draft budget on Thursday, as his government works to reduce the country’s deficit by cutting public spending.
The broad outlines of many of the government’s budget proposals have already been announced, including savings on pensions, a freeze on public-sector salaries and changes to state-funded sick leave.
The deadline for the formal submission of the 2027 Finance Bill to the National Assembly is 6 October. However, the government faces a challenging political environment in a fragmented parliament without a clear governing majority, meaning that pushing the budget through will likely involve difficult negotiations and a potentially arduous parliamentary battle.
In an interview with Le Figaro on 17 September, Prime Minister Sébastien Lecornu said the government planned cuts of around €54 billion, arguing that, without cost-saving measures, the public deficit could approach 6.5% of GDP in 2027 — while the government is targeting a deficit of 5% of GDP.
Lecornu declared that without austerity measures, “the 2027 deficit would approach 6.5% of GDP,” adding that France’s debt burden would increase by “10 billion euros” next year.
“Next year, due to the geopolitical context and rising interest rates, the country will need to find an additional 10 billion euros”, he said.
The government is also considering measures to curb the costs of pensions, notably by limiting their indexation and reducing the tax deduction available to retirees. A reduction in the 10% tax deduction ceiling is expected to generate an additional €1.4 billion for the state.
France’s debt management agency, the Agence France Trésor, announced on Tuesday that the government was set to borrow a record €340 billion, representing €28 billion more than in 2026.
At present, France’s budget deficit is projected to reach 5.4% of GDP this year, one of the largest deficits in the European Union, while public debt nears 120% of GDP. The country’s public debt has climbed to a record level during the two terms of President Emmanuel Macron, unsettling investors and emerging as a defining issue ahead of next year’s presidential election.
Political parties on the left and trade unions have accused the government of implementing “austerity” measures.
Arthur Delaporte, spokesperson for the Socialist Party (PS), described the proposed budget as a “bitter austerity potion”. He argued that it was contrary to Prime Minister Sébastien Lecornu’s stated commitment to come to a “compromise”.
On Tuesday, France’s major public sector unions called for a strike ahead of the budget announcement, with anger mounting, in particular over pay freezes for public-sector workers.
France last balanced its budget in 1973, while maintaining a generous welfare state with strong worker protections. For years, accumulated debt was high — over 90% of annual gross domestic product from 2008 onwards — but manageable due to steady growth and years of near-zero interest rates.