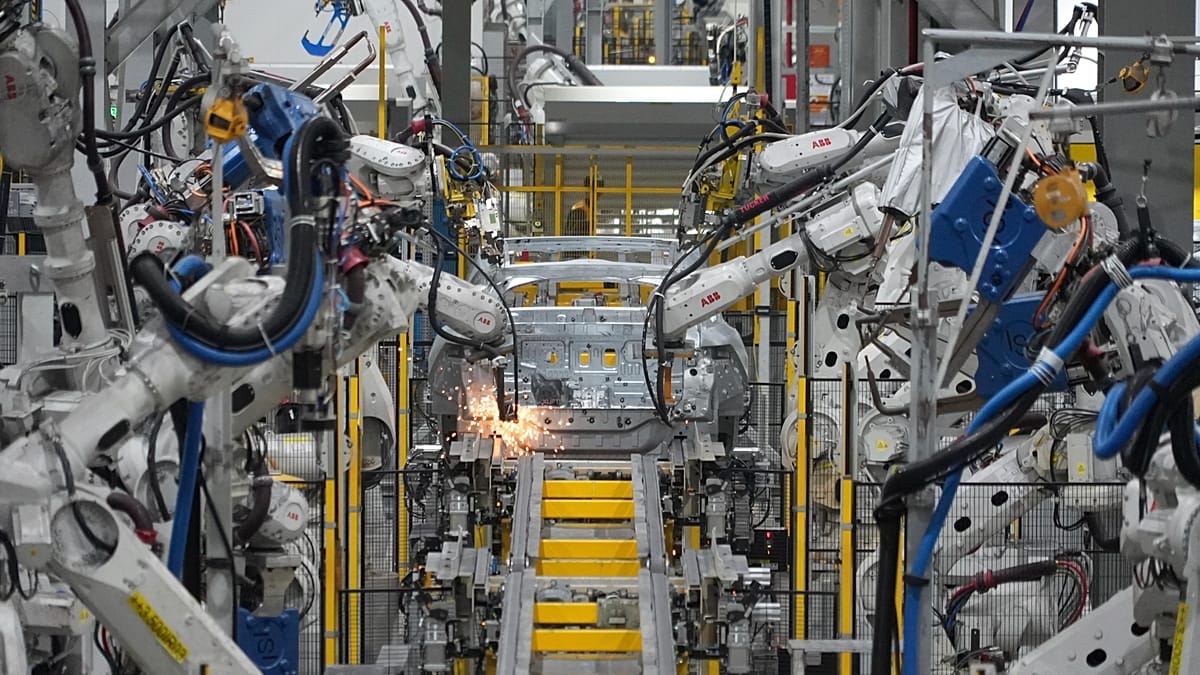
The global operational stock of industrial robots rose 9% last year to reach roughly 5.08 million units, the International Federation of Robotics (IFR) said in its annual World Robotics report published last Thursday.
The IFR is a Frankfurt-based non-profit that has tracked the industry for close to three decades and represents more than 3,000 organisations worldwide.
According to the report, annual installations of industrial robots jumped 11% to surpass 600,000 for the first time, reaching 603,000 units.
“Industrial automation is progressing at high speed,” said Jane Heffner, the IFR’s president, adding that “the new mark of five million robots operational in factories worldwide is more than double the number seven years ago. The strongest growth is taking place in Asia, followed by Americas. Europe is moving ahead more slowly.”
Europe’s more cautious build-up
The slower pace of growth in Europe shows up clearly in the numbers.
The EU’s operational stock passed 700,000 robots for the first time in 2025, reaching 712,000 and accounting for 84% of all robots in operation across Europe.
“The EU’s manufacturing sector has invested significantly in automation,” Heffner said. The stock has grown more than 80% since 2015, when it stood at 390,000.
However, growth has stalled for now.
New installations across the EU fell 11% in 2025 to 60,500 units, even as installations elsewhere accelerated. The bloc’s five-year compound annual growth rate stood at a comparatively modest 3%.
Germany remains by far the largest European market, accounting for 41% of EU installations. But the number of robots installed there fell 8% to under 25,000 as its automotive sector, still the largest single customer, continued to retreat.
Italy, France and Spain follow, each adding between 4,300 and 7,800 robots, with installations in all three down by double digits.
Meanwhile, China widened its lead over the same period, installing 354,000 robots, up 20% and now accounting for 59% of global deployments.
The US also overtook Japan to become the world’s second-largest market, installing almost 38,500 units, up 12%.
A reality check for humanoids
Humanoids remain a tiny market beside established industrial robots.
Only about 7,000 were sold worldwide last year for industrial and professional use, the IFR said in a separate release, the first time it has tracked the category.
Many were bought to generate training data for AI models rather than carry out work, and car manufacturers piloting them typically run fewer than ten machines.
Bank of America nonetheless forecasts 90,000 humanoid shipments this year and 1.2 million by 2030.
The gap between ambition and reality is showing in financial markets too.
Boston Dynamics, owned by Hyundai, is unlikely to pursue a stock listing next year, as its Atlas humanoid has yet to be deployed at scale and the company remains unprofitable, a senior Hyundai executive said this month.
In China, regulators have reportedly used informal guidance to hold back humanoid IPOs after shares in robot maker Unitree soared more than fivefold on their 19 August Shanghai debut, then fell 55% from their peak.
Even Elon Musk has been unusually candid about the difficulty of his own Optimus programme at Tesla.
“This is going to be the hardest product to scale manufacturing that we’ve ever made at Tesla, because everything on the robot is new,” Musk told investors on Tesla’s second-quarter earnings call, adding that “there is no supply chain.”
Where the real value sits
A report published this year by Brussels-headquartered Arthur D. Little, the world’s oldest management consultancy, makes the same point.
“Humanoid robots will capture attention; specialised physical AI will capture value,” it states, using physical AI as an umbrella term for machines, from robot arms to self-driving cars, that can perceive, decide and act in the real world.
It puts that broader market at around $18 billion (€15.8bn) today, of which humanoids account for just $2 billion (€1.75bn) to $3 billion (€2.63bn), and projects that it will reach $60 billion (€52.7bn) to $100 billion (€87.9bn) by 2030.
Many humanoid demonstrations “are fake, AI-generated, or heavily staged”, the report warns, while real ones often show pre-recorded routines or remote human operation.
The sweet spot, it argues, is structured environments such as factories and warehouses, where wheeled robots and fixed arms will scale first because they are cheaper and easier to tailor to specific jobs.
“Why would we limit it to mimic the human form factor…?” asks Dave Grant, CEO of PickNik Robotics, in the report.
Human-level dexterity, reliable autonomy outside controlled settings and the absence of a “killer app” remain major constraints for humanoids, alongside unresolved liability and insurance questions.
Siemens has trialled a robot for logistics tasks at its Erlangen factory, and BMW is deploying a humanoid in car and battery production. But these trials sit alongside the IFR’s conclusion, which suggests that most humanoids remain at the prototype or pilot stage while conventional industrial robots are still more economical for factory work.
Therefore, the world’s robotics story this year is not about humanoids, but about a slower, steadier build-up of machines that already work.