Borrowing money is getting more expensive again.
For most European companies, that is uncomfortable but manageable. For businesses already heavily indebted, it can become a much bigger problem.
Some of the names caught in the squeeze are surprisingly familiar.
They include the company behind Legoland and Madame Tussauds, the owner of Lipton tea, one of Europe’s largest residential property managers and the telecoms empire built by billionaire Patrick Drahi.
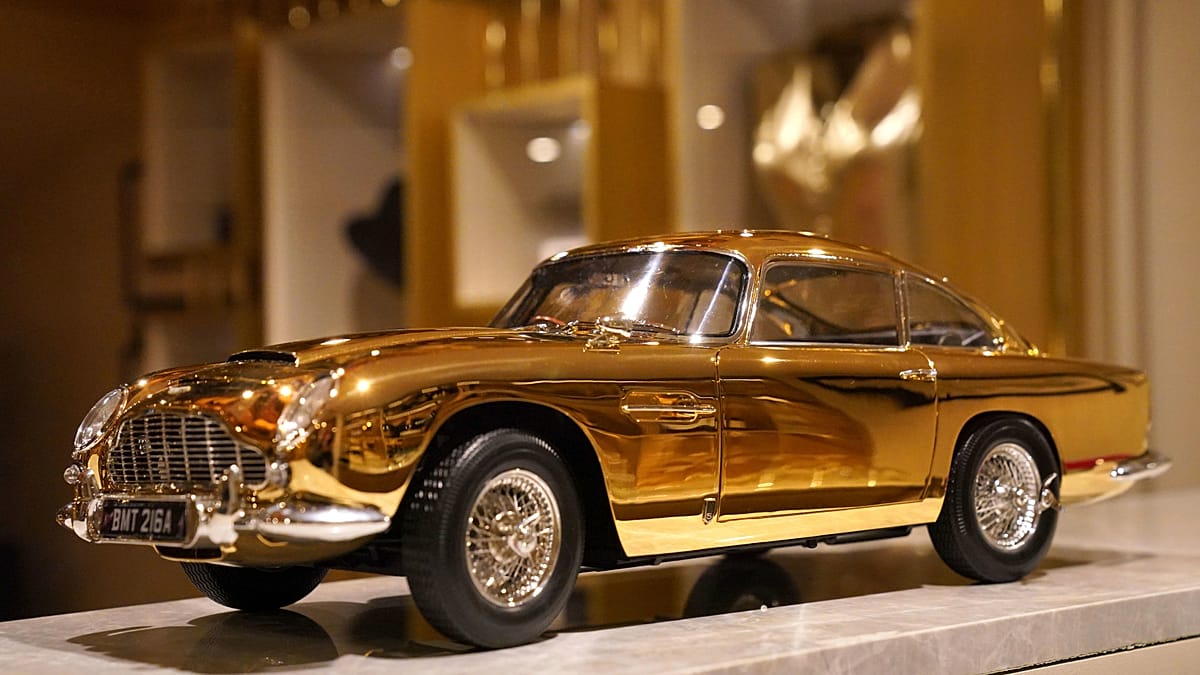
Then there is Aston Martin, the British maker of James Bond’s car.
Many borrowed heavily when interest rates were close to zero.
All sit in, or close to, the CCC area of the credit-rating scale, among the lowest ratings before default.
Now some of that debt is approaching maturity, just as borrowing costs are rising again.
And investors are demanding very high returns to lend them money.
The ECB hiked again: That’s raising the pressure on Europe’s weakest borrowers
After cutting rates through 2025, the European Central Bank has reversed course.
It raised its deposit rate in June, its first hike in nearly three years, as the war involving Iran pushed energy prices and inflation higher.
It followed with a second increase this month, taking the rate to 2.5%.
The US Federal Reserve has done the same, lifting its rate to a range of 3.75% to 4% in September.
For a healthy company, a small rate rise hardly matters.
For a company already struggling with debt, it can be the difference between getting a new loan and not getting one.
“Higher for longer is a slow squeeze for low-quality credit,” Torsten Slok, chief economist at Apollo Global Management, said in a note published on Friday.
In other words, the longer rates stay high, the harder life gets for the weakest borrowers.
Slok added that rate rises are “working with a lag and working unevenly”: they take time to be felt, and they don’t hit everyone equally.
The squeeze can take years to appear because companies do not refinance all their debt at once.
But every maturity brings another test.
A refinancing wall looms
S&P Global Ratings highlighted the 10 largest CCC-rated borrowers held by European collateralised loan obligations, or CLOs, in a report published on 31 July.
The name sounds complicated. The structure is not.
CLO managers essentially buy hundreds of corporate loans and bundle them into portfolios, which are then financed by investors.
S&P found that European CLOs held €5.3 billion of loans to CCC-rated companies maturing in 2028 at the end of June.
That was up sharply from €3.5 billion at the end of 2025.
Six of the 10 largest CCC borrowers identified by S&P face debt maturities in 2027 or 2028.
Here is where the pressure is greatest.
Europe’s 10 most troubled borrowers
10. Colisée
France’s Colisée operates nursing and elderly-care homes in several European countries.
It shows what happens when a debt burden becomes too large.
A Paris court approved its restructuring plan in April. Lenders swapped part of their loans for ownership of the company, and most of its remaining debt was pushed out to 2031.
S&P treated the deal as a default, then upgraded Colisée to CCC+ in May.
That is why its senior debt was yielding only around 5% in S&P’s July snapshot. The pain has already been taken.
9. Stow Group
Belgium’s Stow Group makes warehouse storage systems and automated logistics equipment.
If an Amazon-style warehouse needs racks, shelving or automated storage, Stow operates in that world.
Blackstone is its majority shareholder.
S&P rates it CCC+ with a stable outlook, and European CLOs held €364 million of its loans.
Its next maturity comes in September 2028. Its senior debt yielded around 9% in S&P’s July data.
8. Merlin Entertainments
Merlin owns some of Europe’s best-known attractions, including Legoland parks, Madame Tussauds, Sea Life aquariums and the London Eye.
It is controlled by KIRKBI, the Lego family’s investment company, alongside Blackstone and Canadian pension fund CPP Investments.
European CLOs held €583 million of its loans. S&P’s July snapshot showed its senior debt yielding around 12% to 13%.
Since then, investors have become calmer.
In early September, Merlin secured new financing to deal with debt due in 2027. Its 4.5% euro bond maturing in November 2027 jumped from around 95 cents on the euro to about 98 cents, implying a yield of roughly 6% to 7%.
The bond market is saying Merlin remains highly indebted, but its immediate refinancing risk has eased.
7. Solera
US-based Solera makes software used throughout the motor industry, although its loans are widely held by European funds.
Car insurers use its technology to estimate accident damage, repair shops use it to manage claims and vehicle businesses use its data platforms.
Vista Equity Partners owns the company. S&P rates Solera CCC+, and European CLOs held around €515 million of its debt.
Its next major maturity is in March 2028. S&P’s July snapshot showed its senior debt yielding roughly 11% to 14%.
6. AD Education
AD Education runs private colleges and specialist schools, particularly in design, communication and digital skills.
The French group is majority-owned by private equity firm Ardian.
Its problems are partly operational. S&P downgraded the company to CCC+ in May as profitability came under pressure.
European CLOs held €343 million of its loans. Its debt does not fall due until May 2031, but its senior debt was yielding about 15% in July.
5. Pharmanovia
British-based Pharmanovia sells established and specialist medicines around the world.
Private equity firm Triton Partners is its majority owner. S&P cut the company to CCC+ in January, describing its capital structure as unsustainable.
European CLOs held €485 million of its loans.
Its nearest maturity is further away, in August 2029. But investors are not relaxed: its senior debt was yielding around 17% in July.
4. Lipton Teas and Infusions
Lipton Teas and Infusions owns some of the world’s best-known tea brands, including Lipton, PG Tips, Pukka, T2 and Tazo.
CVC Capital Partners agreed to buy the business from Unilever for €4.5 billion in 2021, and the deal was completed in 2022.
There is nothing inherently risky about selling tea. The risk sits in the financing structure.
S&P rates its parent, Cuppa Bidco, CCC+ with a negative outlook and flags “significant” downside pressure. CLOs held €330 million of its loans.
Its next major maturity is in June 2029. In July, its senior debt was yielding more than 20%.
3. Emeria
Paris-based Emeria, formerly Foncia Groupe, manages residential properties and apartment buildings across Europe. It still uses the Foncia brand in France.
It has built up a heavily leveraged balance sheet under owners Partners Group and TA Associates.
S&P cut it to CCC+ in June, citing persistently high leverage and refinancing risk, and flags “significant” downside pressure.
European CLOs held around €1.1 billion of its loans, the largest amount on the list. Its next significant maturity arrives in September 2027.
S&P’s July snapshot put its senior debt yield at around 17%.
The bond market has since painted an even starker picture.
An Emeria euro bond paying 3.375% and maturing in March 2028 traded at around 74 cents on the euro on 11 September. By 28 September, it had slipped to around 71 cents, implying a yield of about 29%.
2. Arxada
Arxada is a Swiss speciality chemicals company headquartered in Basel.
Its products are used in areas ranging from paints and coatings to hygiene, personal care and wood protection.
Private equity firms Bain Capital and Cinven own the business.
S&P cut it to CCC with a negative outlook in June and flags “high” downside pressure.
Arxada’s problem has already reached the negotiating table.
In May, it agreed a deal with lenders under which its owners would inject CHF 200 million (€211.40 mn) of new money and most of its debt would be extended by about three years, to 2031 and 2032. An English court approved the plan on 15 September.
That buys time. It does not reduce the debt.
European CLOs held €748 million of its loans. Its 4.75% dollar bond, which now matures in 2031 instead of 2028, was quoted at around 87 cents on the dollar in late September.
1. Altice International
Altice International sits within Patrick Drahi’s heavily indebted telecoms empire.
It controls Portuguese telecoms operator MEO and Israeli cable company HOT.
S&P rates it CCC with a negative outlook and flags “high” downside pressure. CLOs hold €525 million of its loans, and its next maturity arrives in February 2027, the soonest on the list.
It also has the weakest recovery prospects in the group. S&P estimates first-lien lenders would get back only about 35% in a default.
In July, its senior debt was already yielding more than 35%.
More recent bond prices are even more striking.
An Altice Financing bond paying 3% and maturing in January 2028 was quoted at around 56 cents on the euro on 28 September, implying a yield of more than 60%.
At those levels, investors are no longer simply asking how much interest Altice will pay.
They are asking how much they might recover if the capital structure has to be changed.
And then there is Aston Martin
Among publicly traded companies, Aston Martin Lagonda Global Holdings offers perhaps the most visible example of Europe’s debt squeeze.
The British luxury carmaker is behind the DB12, Vanquish and Vantage, and its brand is famously associated with James Bond.
Its business is improving in some respects.
First-half revenue jumped 38% to £629 million (€733mn) in 2026.
But Aston Martin still lost £154.2 million (€179.7mn) before tax, while net debt stood at about £1.54 billion.
In July, it raised £550 million (€641mn) of new debt.
The price shows how expensive new financing has become.
The financing carries interest of 6.75 percentage points above SONIA, the benchmark sterling overnight rate, and matures in 2031.
Because those new lenders received stronger claims over assets, S&P subsequently cut Aston Martin’s existing secured notes to CCC and changed the company’s outlook to negative.
The secondary bond market looks even harsher.
Aston Martin’s 10% dollar bond due in March 2029 was quoted at only around 57 cents on the dollar on 28 September. That implies a yield to maturity of about 37%.
The bond market is showing no mercy to James Bond’s carmaker.
Europe does not have a corporate debt crisis
There is one important caveat.
These companies are the weakest tail of Europe’s credit market. They are not the typical European business.
CCC-rated bonds make up just 4.3% of the European high-yield market, according to David Fancourt of M&G Investments, writing on the firm’s Bond Vigilantes blog in August.
The CCC index offered investors 13.06 percentage points of extra yield over government bonds.
The average is pulled up by a small group of companies already in serious trouble, whose bonds trade on what lenders expect to recover in a restructuring.
The same pattern shows up across the wider market. The typical European high-yield bond is priced near its most expensive level in five years.
In other words, healthy companies can still borrow on reasonable terms.
At the other end, bonds issued by Emeria, Aston Martin and Altice now trade at yields between roughly 30% and more than 60%.
Higher interest rates are not crushing corporate Europe uniformly.
They are exposing the companies that borrowed the most when money was cheap, one refinancing deadline at a time.